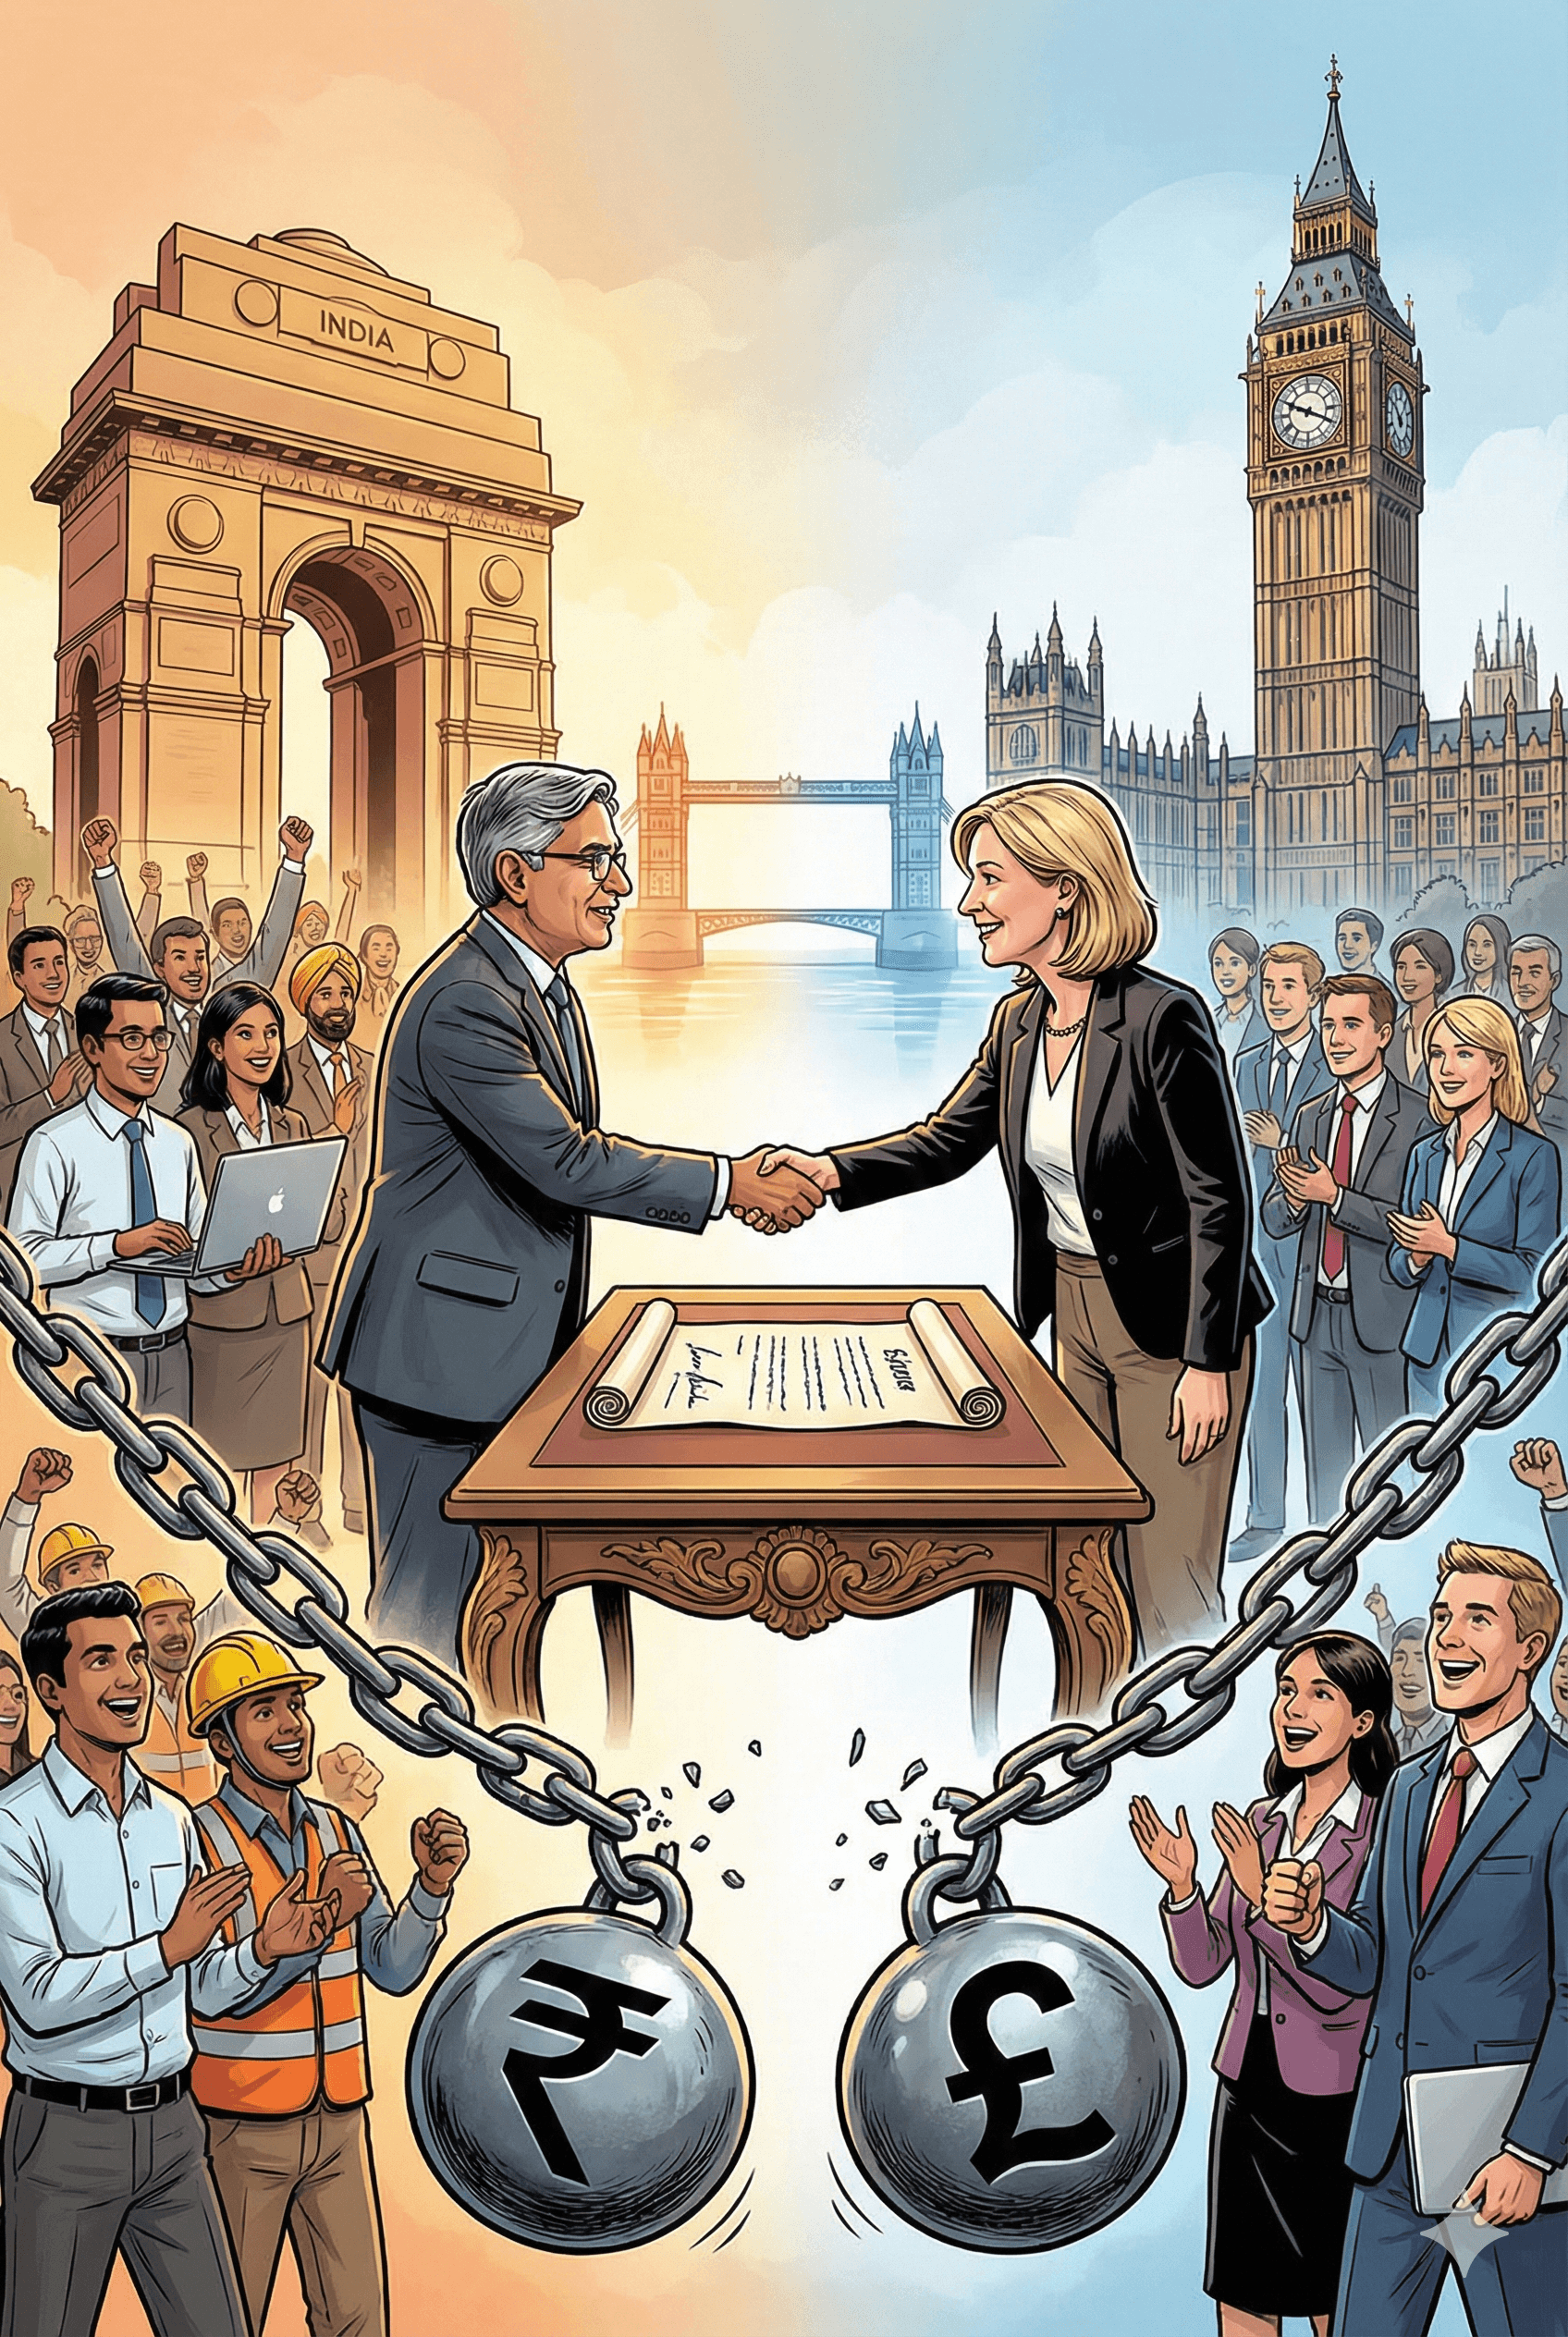
In a significant move to bolster economic ties and ease the financial burden on businesses, India and the United Kingdom have signed a historic social security agreement. The pact, signed on Tuesday, February 10, 2026, in New Delhi, eliminates the requirement for employees on short-term assignments to make social security contributions in both countries.
The agreement was formalized by India’s Foreign Secretary Vikram Misri and the British High Commissioner to India, Lindy Cameron. It marks a critical milestone in the operationalization of the broader India-UK Comprehensive Economic and Trade Agreement (CETA), which the two nations signed in July 2025.
Boosting Workforce Mobility and Reducing Business Costs
For decades, Indian professionals working in the UK and British employees in India have faced the issue of "double taxation" on social security. Under previous regulations, an Indian employee deputed to the UK was required to contribute to the UK’s National Insurance explicitly, despite already contributing to the Employees' Provident Fund (EPF) in India. Since these workers often returned home before becoming eligible for UK state benefits—which typically require ten years of contributions—the payments were effectively a sunk cost for both employees and their employers.
Under the new Double Contributions Convention (DCC), employees temporarily relocated to the other country for a period of up to 36 months will now be exempt from paying into the host country's social security system. Instead, they will continue to make contributions solely to their home country’s scheme.
"This agreement seeks to avoid double social security contributions for employees of both countries on temporary assignments in each other's territories," the Ministry of External Affairs (MEA) stated. "It will support mobility and continued social security coverage of employees on short-term overseas assignments."
Key Provisions of the Agreement
36-Month Exemption: The waiver applies to assignees working in the host country for up to three years.
Certificate of Coverage (CoC): To claim the exemption, employees must obtain a CoC from their home social security agency—the Employees' Provident Fund Organisation (EPFO) in India or HM Revenue and Customs (HMRC) in the UK.
Reciprocity: The deal is fully reciprocal, offering equal benefits to British nationals working in India and Indian nationals working in the UK.
Implementation Timeline: The social security pact will enter into force simultaneously with the India-UK CETA, which is scheduled for implementation in the first half of 2026.
A Major Win for the Indian IT Sector
The agreement is a particular victory for the Indian information technology (IT) sector, which has long lobbied for a "totalization agreement." Indian IT giants like Tata Consultancy Services (TCS), Infosys, and Wipro frequently deploy thousands of software engineers to the UK for project-based work.
Industry estimates suggest that the deal could benefit approximately 75,000 Indian workers, resulting in annual savings of millions of pounds for Indian corporations. These savings are expected to make Indian service providers more competitive in the UK market by lowering the overall cost of deploying talent.
"This removes a significant non-tariff barrier to trade," said an analyst from the Confederation of Indian Industry (CII). "The cost of doing business has just gone down for every Indian firm with a footprint in London, and vice versa for British firms in Mumbai or Bengaluru."
Strengthening the Strategic Partnership
The signing of this specific pact underscores the deepening strategic alignment between New Delhi and London. Following the ratification of the CETA in 2025, both governments have been working rapidly to iron out the technical details required to facilitate free trade.
British High Commissioner Lindy Cameron hailed the agreement as a practical step that directly benefits the workforce. "This reciprocal agreement strengthens ties between our two countries and complements our FTA, which will boost bilateral trade by £25.5bn," she noted.
For the UK, the deal aids its "Global Britain" strategy, making it easier for British firms to send specialized talent to India’s fast-growing market without incurring prohibitive administrative and tax costs.
How to Claim the Benefit
The Ministry of External Affairs has clarified that the signed agreement will be hosted on the websites of both the MEA and the EPFO. Stakeholders are advised to review the protocols for securing a Certificate of Coverage (CoC) ahead of the treaty's formal implementation date later this year. Employers are urged to update their global mobility policies to ensure compliance and maximize the cost-saving benefits for their expatriate workforce.
Outlook: A New Era of Economic Integration
As India and the UK move toward the full implementation of CETA in mid-2026, this social security agreement serves as a concrete example of the benefits of the new trade regime. By resolving a long-standing financial friction point, both nations have signaled their commitment to a seamless exchange of talent and services.
This deal sets a precedent for India’s ongoing trade negotiations with other nations, potentially serving as a template for future social security agreements with the United States and the European Union.
#IndiaUK #TradeDeal #SocialSecurity #GlobalMobility #BusinessNews #Economy #IndiaUKRelations #CETA #ExpatLife #Geopolitics #WorkforceMobility